You’ve heard about infinite banking. Now you want to know: is it actually worth it?
This is the honest breakdown — every real advantage and every real limitation of the Infinite Banking Concept (IBC), drawn from our experience designing 1,000+ policies since 2017. No hype, no sugarcoating, no sales pitch disguised as education.
New to infinite banking? Start with our complete guide to understand how it works before evaluating whether it’s right for you.
TL;DR — Should You Do Infinite Banking?
Infinite banking has real, measurable advantages — but it also has real costs and limitations that most advocates gloss over. Here’s the honest evaluation:
- 10 pros: Non-correlated asset, tax-free access, uninterrupted compounding, guaranteed growth, death benefit leverage, creditor protection, privacy, and more
- 7 cons: Minimum ~$500/month commitment, 4-7 year funding lag, mandatory premiums, discipline required, health qualification, creditor protection variances, single-asset-class concentration
- The deciding factor: 90% of IBC “failures” trace back to poor policy design — not problems with the concept itself
- Best for: Disciplined individuals with stable income, a 7+ year horizon, and a desire to control the banking function in their financial life
- Not for: Anyone who needs every dollar liquid right now, can’t commit $500+/month consistently, or expects stock-market-beating returns from a life insurance policy
Bottom Line: If you have the cash flow, the timeline, and the discipline, infinite banking is one of the most powerful financial strategies available. If you don’t, it will frustrate you. This guide helps you decide which camp you’re in.
Why Trust This Guide
This article is written and maintained by the team at Insurance & Estates — ranked the #1 life insurance agency on Trustpilot with 280+ verified reviews. Our team brings 70+ years of combined experience in estate planning, financial services, and infinite banking policy design. Since 2017, we’ve designed and implemented 1,000+ IBC policies as independent brokers (not captive agents), giving us access to every major mutual carrier. We practice what we teach — our advisors use infinite banking in their own financial lives.
Watch: Infinite Banking Pros and Cons (39 min)
Before you dive into the written breakdown below, this video walks through the same evaluation framework — with policy design examples, real client scenarios, and the nuances that don’t always come through in print. If you absorb information better by watching than reading, start here. The article below covers the same ground in depth and serves as your reference once you’ve seen the bigger picture.
Table of Contents
- Infinite Banking vs Traditional Banking vs 401(k)
- Pros of the Infinite Banking Concept
- Cons of the Infinite Banking Concept
- Next Steps
- Frequently Asked Questions
Infinite Banking vs Traditional Banking vs 401(k)
The Infinite Banking Concept uses dividend-paying whole life insurance as a personal banking system. For a complete explanation of how it works, see our infinite banking guide.
The comparison below shows why practitioners choose to store capital in whole life insurance rather than a bank account or retirement plan — and where each option falls short.
| Feature | Infinite Banking | Bank Savings | 401(k) |
|---|---|---|---|
| Tax-Free Growth | ✅ Yes | ❌ No | ⚠️ Tax-Deferred |
| Tax-Free Access | ✅ Via Policy Loans | ❌ Interest Taxed | ❌ Taxed + Penalties Before 59½ |
| Guaranteed Growth | ✅ Contractual | ⚠️ Near 0% | ❌ Market Risk |
| Creditor Protection | ✅ Most States | ❌ Limited | ✅ ERISA Protected |
| Death Benefit | ✅ Tax-Free | ❌ None | ❌ Taxable to Heirs |
| Access Without Penalty | ✅ Any Time | ✅ Any Time | ❌ Before 59½ |
| Uninterrupted Compounding | ✅ Even While Borrowing | ❌ Withdrawals Stop Growth | ❌ Withdrawals Stop Growth |
| Privacy | ✅ Not on Credit Reports | ❌ Visible in Asset Searches | ❌ Reported to IRS |
| Best For | Long-term wealth building, tax-free liquidity, and financial control | Short-term emergency reserves | Employer-match contributions |
Individual results depend on policy design, carrier selection, and implementation discipline. Consult with a qualified professional before making financial decisions.
The visual below illustrates this difference in action — how traditional financing, conventional saving, and infinite banking each affect your wealth trajectory over time:
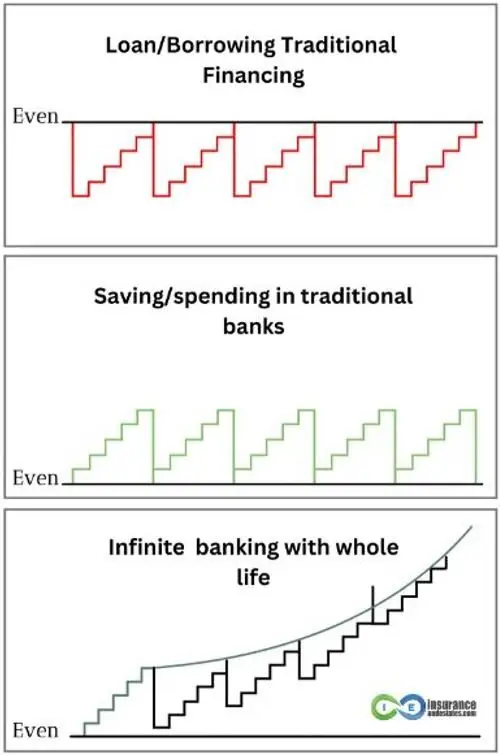
Traditional borrowing depletes your capital every time you finance a purchase. Saving through a bank interrupts compound growth with every withdrawal. Infinite banking keeps your cash value trajectory upward even during borrowing cycles — because you borrow against your policy rather than from it.
Pros of the Infinite Banking Concept
These are the ten advantages that matter most — each one we’ve seen play out firsthand as practitioners and across the clients we’ve served since 2017.
1. Non-Correlated Asset
Whole life insurance doesn’t rise and fall with the stock market, real estate, or interest rate cycles. Your cash value receives guaranteed growth every single year regardless of economic conditions. This matters most during retirement — when markets drop 20-40%, the last thing you want is to draw income from a depleted portfolio. Your infinite banking policy gives you an alternative income source during downturns without forcing you to sell investments at a loss. It’s your financial foundation when everything else is shaking.
2. Improves Cash Flow and Liquidity
Compare accessing your policy’s cash value to accessing equity in real estate. To tap home equity, you need to qualify for a HELOC, get an appraisal, pass a credit check, and wait weeks. With your infinite banking policy, you call the insurance company and request a check. No qualifying, no appraisal, no credit check — funds arrive within days. Your cash value is a true liquid asset that delivers compound growth in a tax-advantaged environment while remaining accessible whenever you need it.
3. Personal Banking System
This is the core of the concept — you own and operate your own banking system. You borrow against your cash value, purchase assets or eliminate debt, use returns from those assets to repay your policy loan, and repeat the cycle indefinitely. The entire time, your full cash value balance keeps compounding through guaranteed returns and dividends. You control the terms, the timing, and the purpose of every transaction. For a full walkthrough of how to implement this, see our guide on becoming your own banker.
4. Tax-Advantaged Compound Interest
Your cash value grows in a true compound interest environment because gains accumulate tax-deferred year after year. Unlike a bank savings account where interest is taxed annually — reducing your compounding base every year — your policy’s growth compounds on the full balance untouched by the IRS. And when you need access to your money, you take tax-free policy loans rather than taxable withdrawals, keeping your principal and compounding engine fully intact. Properly managed, you can use this structure for life without ever triggering a taxable event on the growth.
5. Leverage Through Death Benefit
From day one, your policy provides a tax-free death benefit that can be many multiples of what you’ve contributed. While the death benefit isn’t the primary focus of infinite banking, it provides immediate leverage — peace of mind that your family is protected if something happens to you. And unlike term insurance that expires, your death benefit grows over time as dividends purchase additional paid-up insurance. The older you get, the larger the legacy you leave behind.
6. Tax-Deferred Dividend Growth
Beyond guaranteed cash value growth, your policy earns dividends from the mutual insurance company’s profits. While dividends aren’t guaranteed, the top mutual carriers we recommend have paid dividends every single year for over a century — through the Great Depression, world wars, and every financial crisis in between. When you use dividends to purchase additional paid-up insurance, they compound on top of your existing cash value, accelerating both your accessible capital and your death benefit simultaneously.
7. Tax-Free Access to Cash Value
You access your cash value through policy loans that are tax-free, require no credit check, don’t appear on your credit report, and have no mandatory repayment schedule. You set the terms. Unlike 401(k) withdrawals that trigger taxes and penalties before 59½, policy loans carry none of that. Your entire cash value — including the portion used as collateral — keeps growing tax-deferred while you use the loan proceeds however you choose. This is what makes the banking function truly “infinite.”
8. Guarantees
Whole life insurance is the only financial vehicle that provides all four of these contractual guarantees simultaneously: guaranteed cash value accumulation, guaranteed death benefit, guaranteed fixed premiums, and a guaranteed minimum interest rate. No market-based investment offers this. When your money earns a guaranteed return year after year, it eliminates the pressure to rush into potentially bad investments — you can wait for the right opportunities because your foundation is already growing with certainty.
9. Privacy
In an era where nearly every financial transaction is tracked and reported, whole life insurance stands apart. Your policy’s cash value doesn’t appear on credit reports, asset searches, or standard financial disclosures. Policy loans remain completely private — between you and your insurance company. No bank reporting, no credit score impact, no public record. For business owners, professionals, and anyone who values financial discretion, this level of privacy is a significant and often overlooked advantage.
10. Creditor Protection
Many states provide substantial creditor protection for life insurance cash values — and several offer unlimited protection. If you face financial difficulty, a lawsuit, or a judgment, your policy’s cash value may be sheltered from creditors depending on your state’s laws. This makes whole life insurance not just a growth vehicle but a protective one — particularly valuable for business owners, physicians, real estate investors, and anyone with elevated liability exposure. The level of protection varies by state, so see Con #3 below and our state-by-state guide for specifics.
Key Takeaway — Pros of Infinite Banking
Infinite banking combines benefits that no single traditional financial product can match: guaranteed tax-deferred growth, tax-free access through policy loans, uninterrupted compounding even while borrowing, a growing death benefit, creditor protection, and complete privacy. The most impactful advantage is what practitioners call the “two places at once” mechanism: when you take a policy loan, you’re not withdrawing your cash value — you’re borrowing against it as collateral. Your full cash value keeps compounding inside the policy while the loan proceeds simultaneously fund real estate, business growth, debt elimination, or other opportunities outside the policy. Your dollar does two jobs at the same time.
Cons of the Infinite Banking Concept
We believe honesty about the downsides builds more trust than overselling. These are the real limitations you need to understand before implementing infinite banking — drawn from our experience working with 1,000+ clients since 2017.
1. Cost Prohibitive for Some
Infinite banking requires a meaningful financial commitment — we recommend a minimum of approximately $500/month or 10% of your gross income, whichever is greater. That’s a real barrier for many households. The good news: most people have more capacity than they realize. Our team specializes in identifying “hidden money” — unnecessarily high insurance premiums, inefficient debt structures, or spending patterns that can be redirected without dramatic lifestyle changes. But if you’re stretched thin with no margin, this isn’t the right time to start. Build your financial foundation first.
2. Mandatory Annual Payments
Your policy requires premium payments to stay in force — there’s no way around this. However, a properly designed infinite banking policy builds in flexibility. The required base premium is only 10-20% of your total contribution, while the remaining 80-90% goes toward paid-up additions, which are optional. In practice, your required monthly payment might be just $200 while your full funding target is $1,000. When money is tight, you pay the minimum. When cash flow improves, you fund the full amount. This built-in flexibility is a critical design feature most people don’t know about.
3. Creditor Protection Variances
As noted in Pro #10, creditor protection for life insurance cash value is one of the strongest reasons to own a policy — but the protection isn’t uniform across the country. Some states (Florida and Texas, for example) provide unlimited protection of cash values from creditors and judgments. Others offer partial protection. A few offer little to none. This is a meaningful consideration if you live in a state with weak protections. The silver lining: if you move to a state with stronger protections, you’re generally granted that state’s protections going forward — so a relocation can substantially upgrade your asset protection posture. Consult with an attorney in your state for specifics.
4. Requires Discipline
Nelson Nash said you must be an “honest banker.” That means borrowing against your policy AND paying it back. If you treat your cash value like a piggy bank — borrowing without repaying — you’ll slow the compounding engine and undermine the entire strategy. Infinite banking rewards discipline and punishes carelessness. The long-term growth of your policy depends on cycling loans through your system and recapitalizing your “bank” after each use. This isn’t a set-it-and-forget-it strategy — it requires active participation in your financial life.
5. You Have to Qualify
Infinite banking requires a whole life insurance policy, which means you must pass life insurance underwriting. If you have significant health issues, qualifying can be harder or more expensive. One workaround: you can purchase policies on children or grandchildren and teach them infinite banking principles — building the system for the next generation even if your own health limits your options.
6. Funding Lag Time
This is the con that frustrates people most. When you start an infinite banking policy, your accessible cash value will be less than your total contributions for the first several years. Depending on policy design, the break-even point — where cash value equals or exceeds premiums paid — typically falls between years 4-7. If you need immediate access to 100% of every dollar you contribute, this strategy isn’t for you. But after the break-even point, growth accelerates significantly and the math works powerfully in your favor for decades.
7. Not Diversified (By Itself)
Putting substantial capital into a single asset class raises a valid concern. But here’s the reframe: infinite banking isn’t an investment — it’s financial infrastructure. The guaranteed elements (cash value growth, death benefit, fixed premiums) provide your stable foundation. The real diversification happens at the next level — when you use policy loans to acquire real estate, fund business ventures, purchase dividend-paying stocks, or eliminate high-interest debt. You’re not breaking the diversification rule. You’re applying it at a higher level with a guaranteed base underneath everything.
Key Takeaway — Cons of Infinite Banking
The most significant drawbacks of infinite banking are the upfront cost commitment (minimum ~$500/month), the 4-7 year funding lag before break-even, and the discipline required to repay policy loans consistently. These aren’t dealbreakers — they’re the price of building a banking system you control. Based on our experience, 90% of “failures” with infinite banking trace back to poor policy design rather than problems with the concept itself. Working with a specialist who understands proper policy structuring eliminates most of these risks.
⚡ Beyond Infinite Banking: Volume-Based Banking
If conventional financial advice has left you sensing something’s missing, infinite banking is the foundation — but it’s not the ceiling.
Most financial planning obsesses over rate of return. A 7% return on $50,000 produces $3,500. A 5% return on $500,000 produces $25,000. Same person, radically different financial life — and the difference isn’t rate, it’s volume.
Volume-Based Banking is the framework our team developed for engineering more capital through your banking system in a tax-advantaged environment. It’s not a different product. It’s a different question. Instead of “what’s my return?” the question becomes “how much of my income is moving through a structure I control?” That shift is what separates practitioners building generational wealth from those treating whole life as a savings account with extra steps.
Next Steps
Get Your Personalized Infinite Banking Illustration
Before committing to any strategy, see what the numbers look like for your situation — not a hypothetical case study. Our Pro Client Guides will build a custom illustration around your age, health, income, and goals.
- Custom Illustration: See your projected cash value, death benefit, and loan capacity year by year
- Side-by-Side Comparison: IBC vs your current strategy — 401(k), savings, real estate equity
- Honest Assessment: Whether infinite banking fits your timeline and financial situation
- Lifetime Coaching: Ongoing guidance to optimize your banking system as your situation evolves
- No Obligation: Complimentary session with zero pressure to purchase
Schedule Your Free Strategy Session →
One illustration with your own data is worth more than a hundred articles. — Steve Gibbs, Estate Planning Attorney & Author of The Ultimate Asset
About the Authors
Barry Brooksby — Authorized Nelson Nash Infinite Banking Practitioner, real estate strategist, and author of Live Rich Die Rich. 25+ years in financial services. Barry has designed and implemented over 1,000 IBC policies and personally uses infinite banking to fund real estate investments. Creator of the Amazing Life Agent program.
Steve Gibbs, JD, AEP® — Estate planning attorney, Co-Founder of Insurance & Estates, and author of The Ultimate Asset. 15+ years in trusts, estates, and asset protection law across CA, FL, and MN. Steve brings a legal and wealth-transfer perspective to infinite banking that most insurance-only practitioners lack.
Together, Barry and Steve lead the team at Insurance & Estates — ranked #1 life insurance agency on Trustpilot with 280+ verified reviews.
Frequently Asked Questions
Looking for basics? Our infinite banking guide covers what IBC is, how it works, and whether it’s a scam. Below are the evaluation-specific questions.
Is infinite banking a scam?
No. Infinite banking is a legitimate financial strategy built on dividend-paying whole life insurance — a 160+ year-old product issued by some of the most heavily regulated and conservatively managed financial institutions in the country. The mechanism (borrowing against cash value via policy loans while the full balance continues compounding) is contractually defined in every policy and is the same mechanism corporations and ultra-wealthy families have used for generations. What can be a scam is bad implementation: agents who sell improperly structured policies, oversell expected returns, or push the strategy on clients who shouldn’t have it. The concept is sound. The execution is where most criticism legitimately lands. For a deeper look at common criticisms and how they hold up under scrutiny, see our complete infinite banking guide.
Is infinite banking only for wealthy people?
No. While infinite banking does require consistent funding — we recommend a minimum of around $500/month — it’s not reserved for the wealthy. Many of our clients are middle-income professionals, business owners, and families who redirect existing cash flow rather than finding “new” money. The strategy actually levels the playing field by giving individuals access to the same banking mechanics that corporations and wealthy families have used for over a century. You don’t need to be rich to start. You need stable income, financial discipline, and a long-term perspective.
How much does infinite banking cost?
Most infinite banking policies start at approximately $500/month, though the ideal funding level is around 10-25% of your gross income. The cost depends on your age, health classification, and how aggressively you want to build cash value. Unlike a gym membership or subscription, every dollar of premium builds equity in an asset you own — it’s not an expense that disappears. A 35-year-old male in good health might pay $1,000/month for a $500,000 policy designed for maximum cash value. Our team can show you exactly what the numbers look like for your specific situation with a free custom illustration.
What’s the difference between infinite banking and velocity banking?
They’re completely different strategies that solve different problems. Infinite banking uses whole life insurance to build a permanent, tax-advantaged banking system you control. Velocity banking uses a HELOC (Home Equity Line of Credit) to accelerate debt payoff — primarily your mortgage. Velocity banking is a short-term debt elimination tactic dependent on variable interest rates and lender approval. Infinite banking is a long-term wealth-building system with contractual guarantees and no third-party gatekeepers. Some practitioners use both — eliminating debt with velocity banking while building their IBC policy simultaneously. For a full comparison, see our guide on infinite banking vs velocity banking.
How does infinite banking fit with my 401(k)?
Think complement, not replacement. If your employer offers a 401(k) match, take it — that’s an immediate 100% return. But recognize the 401(k)’s limitations: you can’t access funds before 59½ without penalties, you’re forced into distributions at 73, and every withdrawal is taxed as ordinary income. Your infinite banking policy has none of those restrictions — tax-free access anytime, no required distributions, complete flexibility. The strongest practitioners we work with max out their employer match in the 401(k), then direct additional savings into their banking policy. You get the upfront tax deduction from the 401(k) plus tax-free access and guarantees from whole life.
Can I do infinite banking with an IUL instead of whole life?
Technically yes, but we generally recommend whole life for infinite banking. Indexed Universal Life (IUL) policies tie cash value growth to a market index, which introduces variability that whole life doesn’t have. Whole life provides guaranteed minimums, guaranteed fixed premiums, and a 160+ year track record of dividend payments from mutual carriers. IULs can offer higher potential upside but come with caps, floors, and cost-of-insurance increases that can erode performance over time. For some clients, an IUL component makes sense alongside a whole life foundation. For a detailed breakdown, see our comparison of IUL vs whole life insurance.
How much money do I need to start infinite banking?
You can start an infinite banking policy with as little as $500/month, though higher funding levels produce better efficiency. The real question isn’t the minimum — it’s what you can commit to consistently for 7+ years. Based on our experience with 1,000+ implementations, clients who fund at 10-25% of gross income see the strongest results. You can also add a lump sum upfront to accelerate early cash value growth. Nelson Nash advocated the goal of eventually having your annual premium equal your annual income — but that’s a long-term target, not a starting requirement.
What happens to my money if the market crashes?
This is where infinite banking shines. Your cash value grows regardless of what the stock market does — you receive guaranteed increases every year no matter what’s happening in the economy. The top mutual companies we recommend maintained their dividend payments through the Great Depression, the 2008 financial crisis, and COVID. When credit markets froze in 2008 and banks stopped lending, policyholders could still access their cash value through policy loans — no credit check, no approval process. Even better, recessions create buying opportunities. While others panic-sell at the bottom, you have liquid capital ready to deploy into undervalued assets.
What if the insurance company goes under?
The risk is extraordinarily low — but the answer is more nuanced than most articles let on. State guaranty associations do provide a backstop, typically $100,000 to $300,000 in cash value protection per insured. For a properly funded infinite banking policy held for 20+ years, your cash value will likely exceed those caps — so guaranty associations alone aren’t your primary protection. Your real protection comes from carrier selection. The mutual companies we recommend have AM Best ratings of A or higher, conservative investment portfolios subject to strict state regulation, capital reserves significantly exceeding required minimums, and dividend payment histories spanning more than a century — through the Great Depression, both World Wars, the 2008 financial crisis, and COVID. When carriers do face trouble, state regulators rarely allow outright failure; they facilitate takeovers by stronger companies so policies continue uninterrupted. The combination of conservative carrier selection plus the regulatory framework — not the guaranty association cap — is what makes the carrier-failure risk genuinely small. For specifics on which carriers we recommend and why, see our guide to the top 10 best infinite banking companies.
Can I convert my existing whole life policy to infinite banking?
You typically can’t “convert” an existing policy directly, but you have several options. First, check if your current policy allows adding a paid-up additions rider — this lets you direct more premium toward cash value growth. Second, consider a 1035 exchange, which transfers your existing cash value into a new policy properly structured for infinite banking — completely tax-free. Third, keep your existing policy for what it is and start a new infinite banking policy alongside it. The right path depends on your current policy details, age, health, and goals — this is exactly the kind of situation where working with a specialist makes a significant difference.
What happens to my infinite banking policy when I die?
Your beneficiaries receive the full death benefit minus any outstanding policy loans — completely income tax-free. If you’ve been practicing infinite banking properly and repaying loans, your death benefit will have grown substantially over your lifetime through dividends and paid-up additions. Many practitioners use the death benefit as a wealth transfer tool, funding the next generation’s infinite banking policies or providing a tax-free inheritance. With proper estate planning, your banking system can continue benefiting your family for generations.